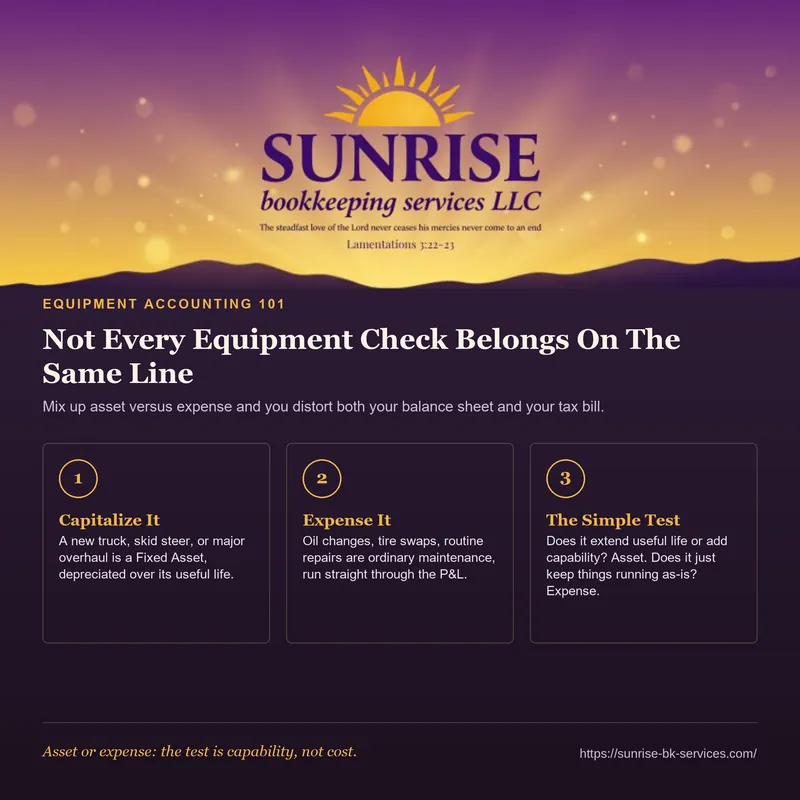
Not every check you write for equipment belongs on the same line of your financials — and mixing them up can quietly distort both your balance sheet and your tax bill.
Here's the line that matters: did the purchase add value or extend the life of something you own, or did it just keep something running the way it already was?
Capitalize it: A new skid steer, a work truck, a trailer, a major engine overhaul that extends useful life — these get recorded as a Fixed Asset on the balance sheet, then depreciated over their useful life (commonly 5 or 7 years for equipment and vehicles under MACRS). You may also be able to elect Section 179 or bonus depreciation to deduct some or all of the cost in the year you place it in service — but that's a tax election layered on top of an asset that's still capitalized on the books, not a reason to expense it outright in your accounting records.
Expense it: Routine maintenance, an oil change, a tire replacement, a repair that just gets a piece of equipment back to normal working condition — these are ordinary repairs and maintenance expenses, run straight through the P&L in the period they happen.
What goes wrong when it's backwards: Expense a real capital purchase and your P&L takes a hit that isn't real: net income looks artificially low that month, your balance sheet understates what you actually own, and if a lender or surety is looking at your financials for a bonding line or equipment loan, your assets look thinner than they are. Capitalize a routine repair instead, and you overstate your assets while understating a real, deductible expense — net income looks better than it should, which can mean overpaying in taxes on a deduction you were entitled to take immediately.
The rule of thumb we use with clients: if it extends useful life or adds capability, it's an asset. If it just keeps things running as-is, it's an expense.
Not sure whether a recent equipment purchase was recorded correctly? Send us a message and we'll take a look.
Have a question about your own books? Call 919-268-6490 or send a message.
Get in touch