If earnest money or client trust funds ever touch your brokerage's operating account, that's not a bookkeeping nuance — it's a compliance problem waiting to surface.
Here's how it should actually work. When a buyer puts down earnest money, or a client hands over funds you're holding on their behalf, that money was never yours. It belongs to the transaction, not the brokerage, until it's disbursed according to the contract or closing statement.
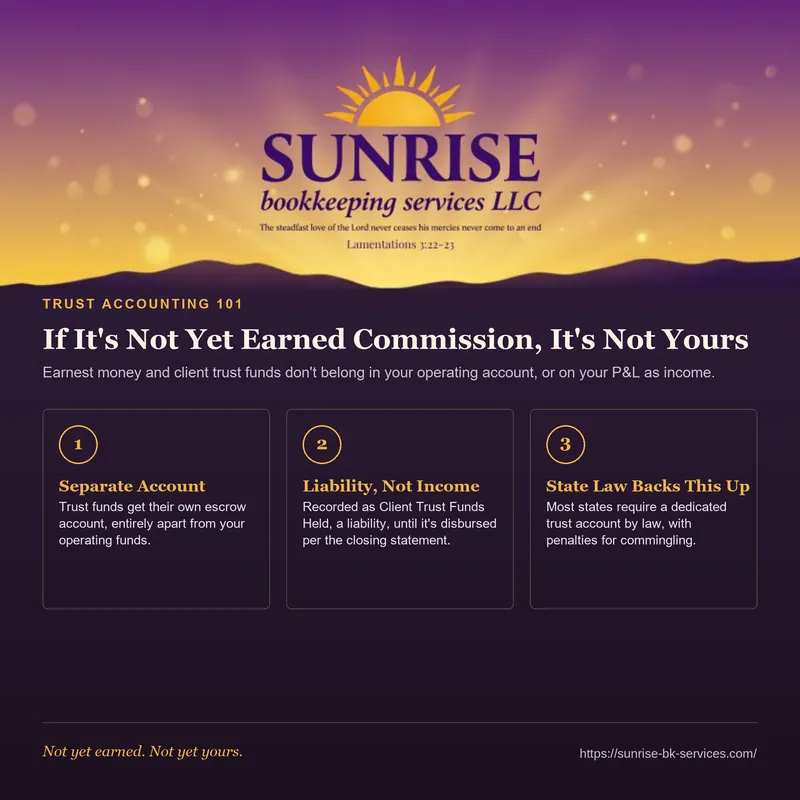
The correct setup: Earnest money and trust funds get deposited into a separate escrow or trust bank account, entirely apart from your operating account, and recorded on the books as a liability (Client Trust Funds Held or similar), not as income. The brokerage's actual income — commissions — only hits the P&L when it's earned and disbursed at closing, per the closing statement.
Why the separation matters beyond the books: Most states' real estate commissions require licensed brokerages to maintain a dedicated trust account and reconcile it regularly, separate from operating funds, with penalties (up to license suspension) for commingling. The accounting has to mirror that legal requirement, or you can be in compliance on paper and still be a mess in practice.
What goes wrong when it's not separated: Deposit earnest money into the operating account and it's easy to lose track of whose money is whose, especially with multiple deals moving at once. Worse, if operating funds run low, that trust money can get spent without anyone intending to misuse it — it just looks like available cash sitting in the account. That's the scenario state trust accounting audits exist to catch, and it's entirely avoidable with the right account structure from day one.
Bottom line: if it's not yet earned commission, it doesn't belong in your operating account or on your P&L as income.
Want a second set of eyes on how your trust accounting is structured? Send us a message.
Have a question about your own books? Call 919-268-6490 or send a message.
Get in touch