A security deposit hitting your P&L as income is one of the most common — and most avoidable — mistakes we see in property management and landlord books.
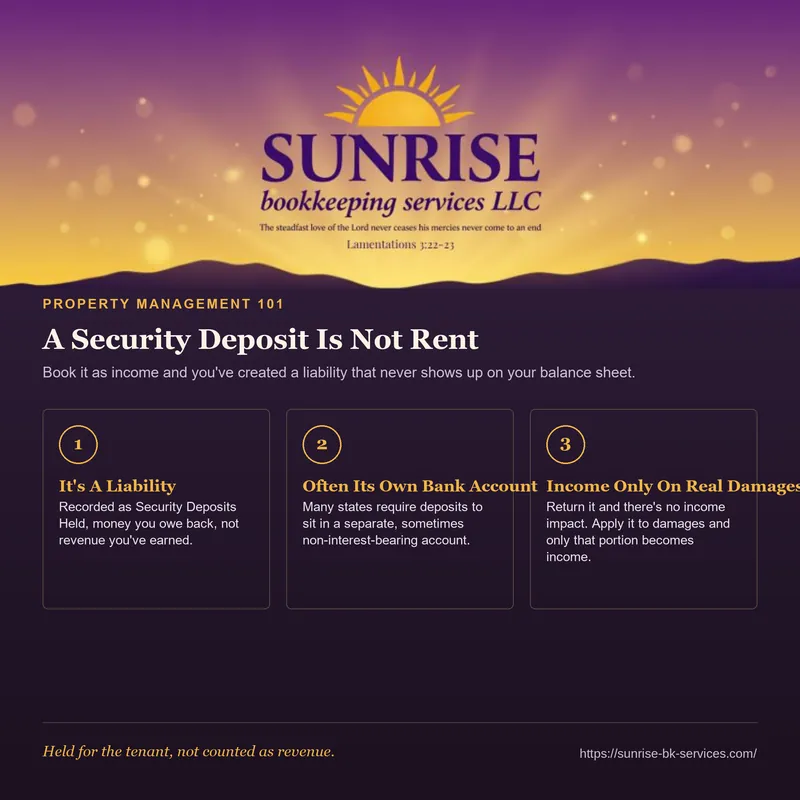
Here's the reality: a security deposit isn't rent, and it isn't yours to spend. It's the tenant's money, held in trust against potential damage or unpaid rent, until the lease ends and you either return it or apply it against actual, documented deductions.
The correct way to book it: When a deposit is collected, it's recorded as a liability (Security Deposits Held), not income, and in most states it needs to sit in a separate bank account from your operating funds — some states even require it to be a segregated, non-interest-bearing account with specific disclosure and interest rules to the tenant. When the tenant moves out, you either return the full deposit (liability clears, no income impact) or apply part of it against damages (a portion moves to income only at that point, for the actual repair cost incurred).
What goes wrong when it's treated as income: Book the deposit as revenue when collected and your P&L looks better than it should the month you receive it — but you've also created a liability you owe the tenant that never appears on your balance sheet. If you commingle it into your operating account, you can end up short when it's time to return deposits at move-out, especially across a portfolio of units, because the cash isn't actually earmarked for anything. And in states with strict trust or escrow requirements for tenant deposits, that commingling itself can be a legal violation independent of whether you ever actually run short.
If you manage rental property: your own or on behalf of owners — deposits deserve their own account and their own line on the books, not a spot in your regular income.
Not sure your security deposit accounting is set up correctly? Send us a message.
Have a question about your own books? Call 919-268-6490 or send a message.
Get in touch