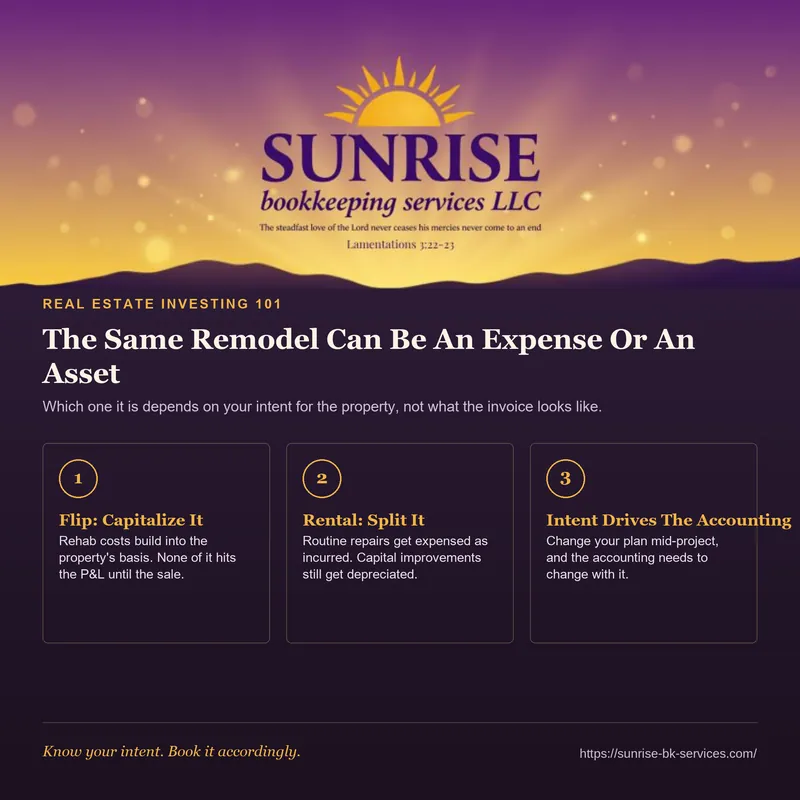
The same $8,000 kitchen remodel can be either an expense or an asset — and which one it is depends entirely on what you're doing with the property, not what the work looks like on the invoice.
Here's the distinction that matters. If the property is a flip — bought with the intent to renovate and resell — nearly all of your rehab costs (materials, labor, permits, even carrying costs like interest and property taxes during the hold) get capitalized into the property's basis, tracked as inventory or work-in-progress. None of it hits the P&L as an expense along the way. When the property sells, that accumulated basis becomes Cost of Goods Sold, and profit is recognized in one shot at closing.
If the property is a buy-and-hold rental, the accounting splits differently. Standard repairs and maintenance — patching drywall, fixing a leak, replacing a broken appliance — get expensed as incurred, right on the P&L, reducing taxable rental income in the year they happen. But capital improvements — a new roof, a full kitchen renovation, an addition — still get capitalized and depreciated over their useful life, not expensed outright, even on a rental you're keeping.
Where this gets muddy: Treat a flip's rehab costs as period expenses instead of capitalizing them, and your P&L shows a loss every month you're renovating, even though you're building real equity in an asset that will show a large profit at sale — a picture that's misleading to you and to any lender reviewing your financials mid-project. Treat a rental's genuine capital improvement as a current expense instead of depreciating it, and you understate the property's basis and overstate this year's deduction (and then face inconsistent numbers if the IRS or a lender ever asks). Mix the two strategies on the same property — say, you bought as a flip but decided to hold and rent it instead — and the accounting needs to be adjusted at that decision point, not left running on autopilot from the original plan.
The intent behind the property drives the accounting, and that intent needs to be documented and consistent. Send us a message if you'd like help getting your rehab or renovation costs categorized correctly.
Have a question about your own books? Call 919-268-6490 or send a message.
Get in touch